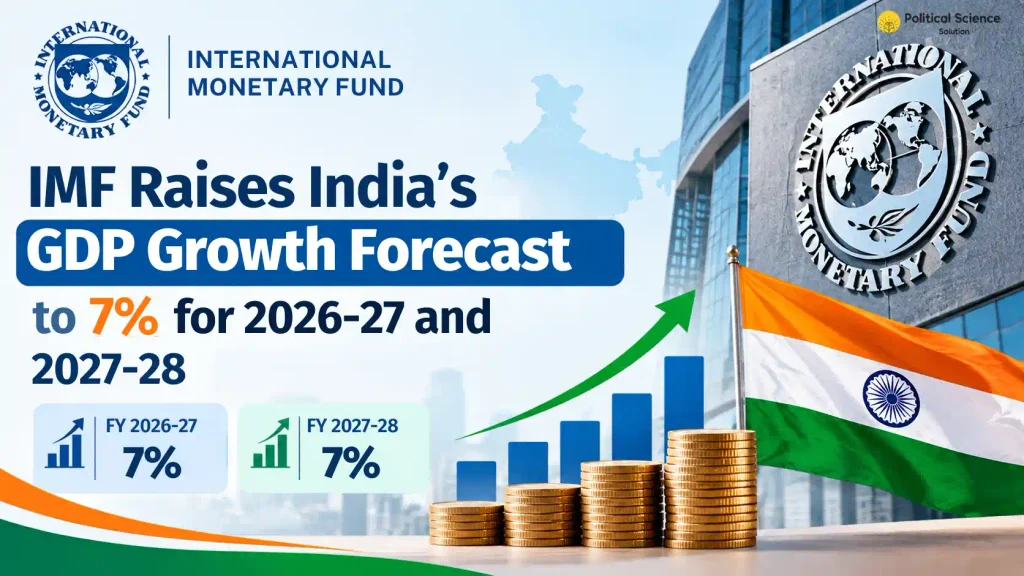
New Delhi: The International Monetary Fund has revised India’s growth projections sharply higher in its latest World Economic Outlook update, setting the stage for the country to remain the standout performer among major economies. The Fund now expects India’s GDP to expand at 7 percent in both 2026-27 and 2027-28. These figures mark clear improvements over the July estimates of 6.4 percent and 6.7 percent respectively. The revision arrives against a backdrop of resilient domestic demand, robust services activity, and a series of supporting assessments from other global institutions.
IMF’s Upward Revision for India and Alignment with RBI
The updated forecast places India’s growth at 7 percent for the fiscal year 2026-27, a full 0.6 percentage point above the previous projection. For 2027-28 the outlook has also been lifted to 7 percent. The IMF attributed the change to stronger-than-expected momentum that has continued to outpace earlier expectations. This assessment comes just one week after the Reserve Bank of India raised its own growth estimate for the current year to 7.1 percent. The close alignment between the central bank and the multilateral institution reflects shared confidence in recent data, particularly the 7.8 percent expansion recorded in the April-to-June quarter. That quarterly performance was driven by solid private consumption and sustained strength in the services sector, creating a carry-over effect that underpins the higher annual numbers.
Drivers of the Stronger Growth Outlook
In its commentary the IMF highlighted several structural factors that set India apart. The institution pointed to favourable demographic dynamics, a large and expanding domestic market, and the continued pursuit of structural reforms as evidence of stronger underlying growth potential. These elements, combined with resilient domestic demand and robust services activity, have allowed the economy to maintain momentum even as external conditions remain complex. The Fund described India as standing out with upward revisions, underscoring the sustained nature of the current expansion.
Oil Price Assumptions and Geopolitical Pressures
Energy costs form an important part of the IMF’s framework. The average price of crude oil—calculated across Brent, Dubai Fateh, and West Texas Intermediate—is projected at 95.74 dollars per barrel in 2026. That level represents a 41 percent increase from 2025. For 2027 the assumption is a decline of roughly 9 percent to 87.39 dollars per barrel. Separate commentary had earlier referenced an average near 82 dollars with a 21.4 percent rise, illustrating the range of scenarios under consideration. Despite these higher oil prices, the IMF noted that India’s growth remained robust, supported by domestic demand and services. The revision comes in the face of ongoing geopolitical uncertainties, including the US-Iran conflict and the Russia-Ukraine war, both of which carry implications for energy-dependent economies. The Fund’s judgment is that internal drivers have so far proved sufficient to absorb the impact of elevated energy costs.
Global Growth Context and India’s Distinct Role
The sharper outlook for India stands in clear contrast to the broader global picture. World growth is now projected at 3.1 percent in 2026, only a slight improvement from the 3 percent estimated in July. The 2027 forecast remains unchanged at 3.4 percent. Within this environment India is positioned as a primary contributor to global expansion. The IMF’s language emphasises that the country’s higher trajectory helps offset softer performances elsewhere and reinforces its role as a growth engine at a time when many other major economies face more constrained prospects.
Advanced Economies Register Modest Improvements
The Fund has become more optimistic about several advanced economies. Overall, this group is now expected to grow by 2.1 percent in 2026, compared with the 1.7 percent rate estimated in July. Germany’s forecast has been raised to 1.3 percent from 0.7 percent, while the United Kingdom’s projection has moved to 1.3 percent from 1 percent. These upgrades reflect a somewhat brighter reading of activity in key developed markets, yet the absolute rates remain well below India’s projected pace.
Emerging Markets and Developing Economies Face a Softer Outlook
In contrast, the outlook for emerging markets and developing economies has weakened slightly. The IMF now expects this grouping to expand by 3.7 percent in 2026, down from the 3.8 percent projected in July. The downgrade occurs even after the sharp upgrade to India’s numbers and is driven mainly by slower growth or contraction expected in China, Russia, Brazil, and several Middle Eastern economies. These weaker performances weigh on the aggregate outlook for the emerging-market category and further highlight India’s relative strength.
Consensus Across International Institutions
India’s improved prospects are not limited to the IMF. Last month the Asian Development Bank, the Organisation for Economic Co-operation and Development, and rating agencies including S&P and Fitch also raised their projections for India’s FY27 GDP growth to around 7 percent. These adjustments were prompted by robust June-quarter economic activity and the persistence of domestic demand despite Middle East-related disruptions. The convergence of views across multiple institutions points to a shared assessment that India’s near-term capacity has been underestimated in earlier forecasts.
Questions on Prosperity Beyond the Headline Numbers
While the growth-rate revisions have drawn widespread attention, parallel analysis has stressed that a single number reflecting macro-production activity does not tell the full story. One detailed commentary observed that attention must also be paid to the context in which growth occurs. Despite the relative expansion of the overall economy, informality across sectors in India continues to widen. This observation underscores that aggregate output gains, however impressive, leave open important questions about employment quality, income distribution, and the extent to which formal-sector opportunities are reaching broader sections of the population. The discussion of prosperity therefore remains distinct from the discussion of headline growth rates.
Earlier Assessments and the Impact of Trade Measures
An earlier IMF assessment released in October 2025 had taken a more measured stance under different external conditions. At that time the Fund raised its projection for India’s 2025-26 fiscal year by 0.2 percentage points to 6.6 percent, citing strong first-quarter momentum that more than offset the increase in the US effective tariff rate on imports from India. The same report lowered the subsequent year’s forecast by 0.2 percentage points to 6.2 percent. Those adjustments came against the backdrop of steep tariffs, in some cases reaching 50 percent, imposed on Indian goods. Emerging-market and developing-economy growth was then expected to moderate from 4.3 percent in 2024 to 4.2 percent in 2025 and 4 percent in 2026. Higher US tariffs were described as curtailing external demand, while rising trade-policy uncertainty weighed on investment in export-oriented economies. The shift from those 2025 numbers to the current 7 percent outlook for both 2026-27 and 2027-28 illustrates how quickly the assessment of India’s domestic resilience has evolved.
Broader Implications for Policy and Global Positioning
The successive upward revisions by the IMF, the Reserve Bank of India, the Asian Development Bank, the OECD, and major rating agencies form a consistent narrative of an economy that continues to outperform earlier expectations. Domestic demand and services have repeatedly demonstrated durability in the face of external headwinds, whether in the form of elevated oil prices, geopolitical conflicts, or earlier tariff pressures. Favourable demographics and the scale of the internal market are repeatedly cited as foundations for this continued strength. At the same time, the global environment remains fragmented. Advanced economies show only modest improvement, while several large emerging economies face slower expansion. Oil-price volatility and ongoing geopolitical tensions add further layers of uncertainty.
Within this setting the IMF’s decision to place India’s growth at 7 percent for both the current and the following year underscores the country’s distinctive position. The projection not only confirms India’s status as the fastest-growing major economy but also positions it as a central contributor to global expansion at a moment when many other economies are expected to advance more slowly. The accompanying discussion of informality and the incomplete translation of growth into broad-based prosperity serves as a reminder that headline numbers capture only one dimension of economic performance. Policymakers and observers will continue to watch both the delivery of the projected growth rates and the quality of the expansion that follows.
FAQs
1. What is the IMF’s latest GDP growth forecast for India?
The International Monetary Fund has raised India’s GDP growth projection to 7 percent for both 2026-27 and 2027-28. This marks an increase from the July estimates of 6.4 percent for 2026-27 and 6.7 percent for 2027-28. The revision comes shortly after the Reserve Bank of India lifted its own growth estimate for the current year to 7.1 percent, supported by the 7.8 percent expansion recorded in the April-June quarter.
2. Why did the IMF upgrade India’s growth outlook?
The Fund cited stronger-than-expected momentum driven by resilient domestic demand and robust services activity. It also highlighted favourable demographic dynamics, a large and expanding domestic market, and continued structural reforms as evidence of stronger underlying growth potential. These factors have allowed India to maintain solid performance despite external pressures.
3. How does India’s projected growth compare with the rest of the world?
India is expected to remain the fastest-growing major economy. Global growth is projected at 3.1 percent in 2026 (slightly higher than the previous 3 percent) and unchanged at 3.4 percent in 2027. Advanced economies as a group are forecast to expand by 2.1 percent in 2026 (up from 1.7 percent), with Germany and the United Kingdom both revised to 1.3 percent. Emerging markets and developing economies are expected to grow at a slightly weaker 3.7 percent in 2026 (down from 3.8 percent), weighed down by slower performances in China, Russia, Brazil and several Middle Eastern economies.
4. What assumptions has the IMF made about oil prices and geopolitical risks?
The IMF assumes average crude oil prices (across Brent, Dubai Fateh and West Texas Intermediate) will reach 95.74 dollars per barrel in 2026—a 41 percent rise from 2025—before easing about 9 percent to 87.39 dollars in 2027. Despite higher oil costs and ongoing geopolitical uncertainties linked to the US-Iran conflict and the Russia-Ukraine war, the Fund noted that India’s growth has remained robust, supported by domestic demand and services.
5. Do the higher growth numbers fully reflect economic prosperity in India?
While the 7 percent forecasts indicate strong macro-level expansion, analysts caution that a growth-rate figure alone does not capture the complete picture. One detailed assessment points out that informality across sectors continues to widen, raising questions about employment quality, income distribution and the extent to which formal-sector opportunities reach broader sections of the population. Headline growth therefore needs to be viewed alongside these deeper structural considerations.