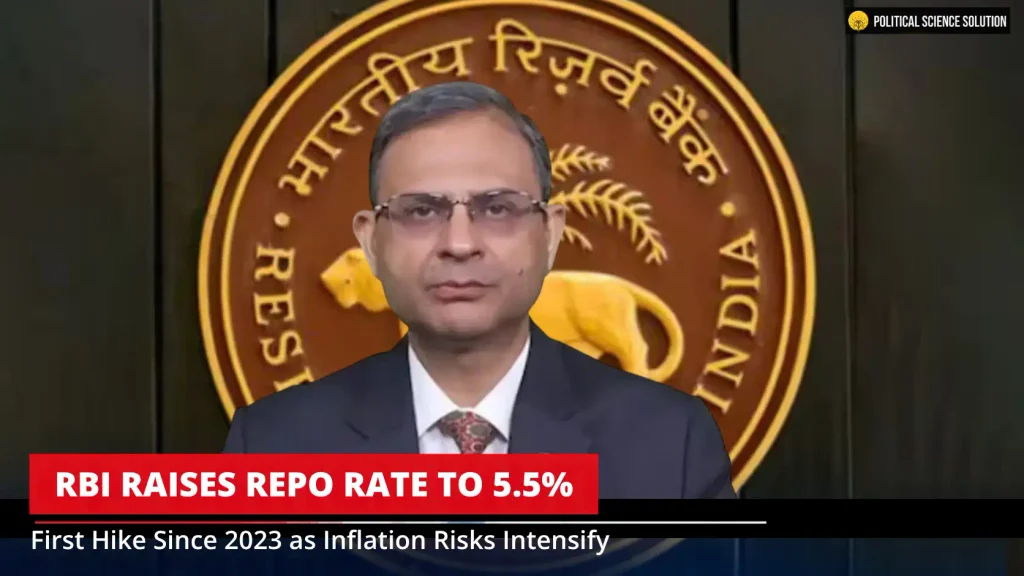
New Delhi: The Reserve Bank of India has delivered its first policy rate increase in nearly four years, lifting the repo rate by 25 basis points to 5.5 percent. The unanimous decision by the Monetary Policy Committee on October 7, 2026, comes amid mounting inflation pressures driven by geopolitical tensions in West Asia, elevated global oil prices, a weaker rupee, and domestic supply disruptions. The move signals a decisive pivot toward containing price risks while the Indian economy continues to display underlying strength.
Details of the Rate Decision and Background
The Monetary Policy Committee, headed by Governor Sanjay Malhotra, voted unanimously to raise the policy repo rate under the liquidity adjustment facility from 5.25 percent to 5.50 percent. This marks the first increase since February 2023, which had concluded the post-pandemic tightening cycle. Through most of 2025 the central bank had reduced rates in phases, bringing the repo rate down by a cumulative 125 basis points from 6.50 percent to 5.25 percent by December 2025. The rate was then held unchanged across the subsequent four meetings until the latest action.
The decision aligns with market expectations and mirrors tighter monetary settings adopted by several global central banks responding to energy-driven inflation linked to the ongoing conflict in the Middle East. India’s benchmark equity indices reacted with declines as investors weighed the implications of higher borrowing costs for consumption and corporate investment. The Sensex and Nifty both fell on the day of the announcement, with rate-sensitive sectors leading the losses.
Shift in Monetary Policy Stance to Calibrated Tightening
In a notable change, the committee revised its monetary policy stance from “neutral” to “calibrated tightening.” This is the first such shift since 2018. A neutral stance had kept all options open, allowing the central bank to raise or cut rates depending on evolving inflation and growth data. Calibrated tightening, by contrast, indicates a clear lean toward tighter policy. It signals that rate cuts are off the table in the near term while leaving open the possibility of further increases if inflationary pressures persist. The stance remains data-dependent, with decisions to be measured against macroeconomic developments. Two members of the six-member committee dissented on the stance change even as they supported the rate hike itself.
Governor Malhotra explained that the “calibrated” qualifier reflects a milder and more measured form of tightening that will respond carefully to incoming information rather than following a predetermined path.
Inflation Outlook Revised Higher Amid Supply Pressures
The Reserve Bank has raised its Consumer Price Index inflation projection for the financial year 2026-27 to 5.2 percent from the earlier estimate of 5 percent. Core inflation is now forecast at 4.4 percent, a modest upward revision from 4.3 percent. Headline inflation is expected to average nearly 5.8 percent over the next three quarters, rising to around 6 percent in the third quarter and 5.7 percent in the fourth quarter.
Governor Malhotra highlighted that inflation risks are no longer as benign as they appeared a year earlier. Food price increases have become more broad-based, with notable spikes in sugar and onion. Early signs point to inflation becoming generalised, as core inflation rises and a larger share of the CPI basket records elevated price increases. Near-term pressures are expected to stem primarily from the supply side, driven by a deficient southwest monsoon, possible El Niño conditions, and high volatility in international oil prices. Price pressures are increasingly visible across a range of commodities.
Crude oil has been trading above 100 dollars a barrel. India imports approximately 90 percent of its crude oil and 50 percent of its gas needs, so elevated global prices, combined with a rupee trading near multi-month lows against the dollar, translate into higher domestic costs. The central bank continues to target headline inflation at 4 percent over the medium term while monitoring underlying inflation dynamics, diffusion indices, and second-round effects.
Growth Forecast Upgraded Despite Global Headwinds
Even as it tightened policy, the Reserve Bank raised its real GDP growth projection for 2026-27 to 7.1 percent, an upward revision of 40 basis points from the previous 6.7 percent estimate. The upgrade follows stronger-than-expected performance in the first quarter and sustained momentum into the July-September period.
Manufacturing activity has held up despite cost pressures. The services sector remains steady and broad-based. Fixed investment continues to show strength. Private consumption and investment are expected to remain the primary drivers of growth, while net exports have stayed positive. The World Bank had also recently raised its India growth forecast to 7.1 percent, citing the better first-quarter print.
Some soft patches remain. The central bank flagged weakness in non-durable goods and domestic air traffic. Supply-chain disruptions linked to global uncertainty could weigh on activity. A weak monsoon and the risk of El Niño conditions may affect the rabi season. Nevertheless, both rural and urban demand are expected to stay sustained, supporting overall resilience.
Governor’s Guidance on Future Policy Path
In his post-policy remarks, Governor Sanjay Malhotra emphasised that the Indian economy remains strong and that economic momentum is broad-based. The global context, however, stays challenging because of geopolitical developments. Rate cuts are off the table in the near term. Future policy action can only take the form of a further rate hike or a pause, depending on the evolution of growth and, especially, underlying inflation.
The extent and duration of any rate-hike cycle will be contingent on actual growth outcomes, the path of underlying inflation, the degree to which price pressures broaden, and the second-round effects of supply shocks. The Reserve Bank will continue to strive for both price stability and financial stability, viewing both as essential for sustainable long-term growth. Liquidity management tools will be deployed to keep system liquidity in check while efforts continue to limit excessive volatility in the rupee.
Foreign-exchange reserves remain healthy and provide import cover for about 11 months. The balance of payments is expected to record a healthy surplus this year. On the currency, Malhotra observed that markets can behave irrationally in the short run. Multiple measures, including the real effective exchange rate, suggest the rupee may currently be undervalued rather than overvalued.
Impact on Borrowing Costs and Key Sectors
The 25-basis-point increase is expected to raise the cost of funds for commercial banks, which will in turn pass on higher rates to customers. Home loans, vehicle loans, personal loans, and corporate credit are likely to become more expensive. Existing borrowers on floating-rate facilities may see their equated monthly installments rise.
In the real-estate sector, the festive period is traditionally a key window for housing demand. Higher borrowing costs are expected to weigh on buyer sentiment, particularly in price-sensitive and affordable segments. Decision timelines may lengthen as households recalculate budgets. Commercial real estate is viewed as more resilient, supported by structural demand from global capability centres, technology firms, and banking and financial services. Retail real estate could face some near-term pressure.
Non-banking financial companies will encounter higher funding costs. Disciplined pricing, diversified funding sources, and prudent underwriting will become more important even as underlying credit demand remains healthy. Manufacturers already dealing with elevated energy and input costs will face a marginal increase in the cost of capital. Export-oriented industries have been advised to prepare for higher borrowing costs going forward, even as engineering goods exports have shown resilience with strong double-digit growth in the early months of the financial year.
Expert and Industry Reactions
Market participants described the rate hike as largely in line with expectations, though the shift in stance to calibrated tightening came as a mild surprise to some. Private-sector economists continue to see scope for an additional 25 to 50 basis points of tightening if global risks persist.
Industry voices acknowledged the need to address inflation while underscoring the importance of supporting growth. Real-estate consultants highlighted potential near-term effects on housing demand. NBFC leaders characterised the move as measured and stressed the need for quality-led growth. Manufacturing representatives called for continued attention to supply-side constraints alongside the calibrated monetary approach.
Additional Regulatory and Developmental Measures
Alongside the rate decision, the Reserve Bank announced steps to improve customer convenience. It will facilitate interoperability among NBFC Account Aggregators, allowing customers to access and share financial information across different service providers through any account aggregator of their choice. The central bank is also enabling SEBI-regulated depositories to include bank deposit account information in the consolidated account statement. Demat account holders will therefore be able to view both securities holdings and bank deposit details in a single statement.
Global Context and Risks
The Indian policy action occurs against a backdrop of tighter global financial conditions. The US Federal Reserve has raised rates in recent months, supporting higher Treasury yields and a strong dollar that has encouraged capital outflows from emerging markets. Elevated valuations of artificial-intelligence-related assets have been flagged by the Reserve Bank as one of the key downside risks to the global outlook, alongside geopolitical tensions, tighter financial conditions, and high public debt. The unresolved nature of the West Asia conflict continues to add uncertainty around trade and supply chains.
Looking Ahead
The next meeting of the Monetary Policy Committee is scheduled for December 2 to 4, 2026. Markets will watch incoming inflation and growth data closely for clues on whether further tightening will be required. By combining a measured rate increase with an upgraded growth forecast and clear communication that rate cuts are not under consideration in the near term, the Reserve Bank has sought to anchor inflation expectations while recognising the resilience of the domestic economy. The coming months will determine how effectively the calibrated tightening stance balances the twin objectives of price stability and sustained growth in an unsettled global environment.
Frequently Asked Questions
1. Why did the Reserve Bank of India raise the repo rate in October 2026?
The RBI increased the repo rate primarily to address rising inflation risks that were no longer as benign as a year earlier. Key drivers included challenging geopolitical developments linked to the ongoing West Asia conflict, high volatility in international oil prices (crude trading above $100 a barrel), a weaker rupee near multi-month lows, weather disruptions, a deficient southwest monsoon, and possible El Niño conditions. These factors led to broader food price increases (including spikes in sugar and onion) and early signs of inflation becoming more generalised across the CPI basket. The central bank noted that global inflation is expected to rise, trade uncertainty persists, and supply-chain disruptions remain a concern, even as the Indian economy stays resilient.
2. What exactly changed in the latest monetary policy decision?
The Monetary Policy Committee unanimously raised the policy repo rate by 25 basis points from 5.25% to 5.50%. This was the first increase since February 2023, after a period of rate cuts in 2025 that brought the rate down by 125 basis points overall, followed by a hold from December 2025. The committee also shifted its monetary policy stance from “neutral” to “calibrated tightening” (the first such change since 2018). A neutral stance had kept options open for either hikes or cuts; calibrated tightening signals a lean toward tighter policy, with rate cuts explicitly off the table in the near term while further hikes remain possible if inflation risks worsen. Two members dissented on the stance change but supported the rate hike. Governor Sanjay Malhotra stated that future action can only be a further hike or a pause, depending on data.
3. How have the inflation and growth forecasts been updated?
The RBI revised its CPI inflation projection for FY 2026-27 upward to 5.2% from the earlier 5%, with core inflation now at 4.4% (up from 4.3%). Headline inflation is expected to average nearly 5.8% over the next three quarters, rising to about 6% in the third quarter and 5.7% in the fourth. At the same time, the real GDP growth forecast for FY 2026-27 was raised by 40 basis points to 7.1% from 6.7%, reflecting stronger-than-expected first-quarter performance and continued momentum in manufacturing, services, fixed investment, private consumption, and positive net exports. Soft spots remain in non-durable goods, domestic air traffic, and potential monsoon-related effects on the rabi season.
4. How will the rate hike affect ordinary borrowers and different sectors?
Higher borrowing costs are expected for home loans, car loans, personal loans, and corporate credit, as banks pass on the increased repo rate. Existing floating-rate borrowers may see higher EMIs. In real estate, the festive season housing demand could face pressure, with buyers becoming more selective and decision timelines lengthening, especially in affordable and price-sensitive segments; commercial real estate is seen as more resilient due to structural demand from GCCs, technology, and BFSI. NBFCs will face higher funding costs, requiring disciplined pricing and prudent underwriting, though credit demand remains healthy. Manufacturers already dealing with elevated energy and input costs will see a marginal rise in the cost of capital. Exporters have been advised to prepare for higher borrowing costs even as engineering goods exports have shown resilience.
5. What did RBI Governor Sanjay Malhotra say about the outlook and next steps?
Governor Malhotra emphasised that the Indian economy remains strong with broad-based momentum and is expected to stay resilient despite a challenging global context. He stated that rate cuts are off the table for now and that the central bank will focus on bringing headline inflation toward the 4% target while monitoring underlying inflation, core trends, and second-round effects. The extent and duration of any further tightening will depend on actual growth, the path of inflation, and how broadly price pressures spread. The RBI will use liquidity tools to manage system liquidity and curb excessive rupee volatility. Forex reserves remain healthy (covering about 11 months of imports), and the balance of payments is expected to show a healthy surplus. The next MPC meeting is scheduled for December 2–4, 2026. Additional measures announced include interoperability among Account Aggregators and inclusion of bank deposit details in demat consolidated account statements for greater customer convenience.